Last Thursday, the credit card charge at the bottom of the bill disappeared. Diners cheered. Operators did the maths.
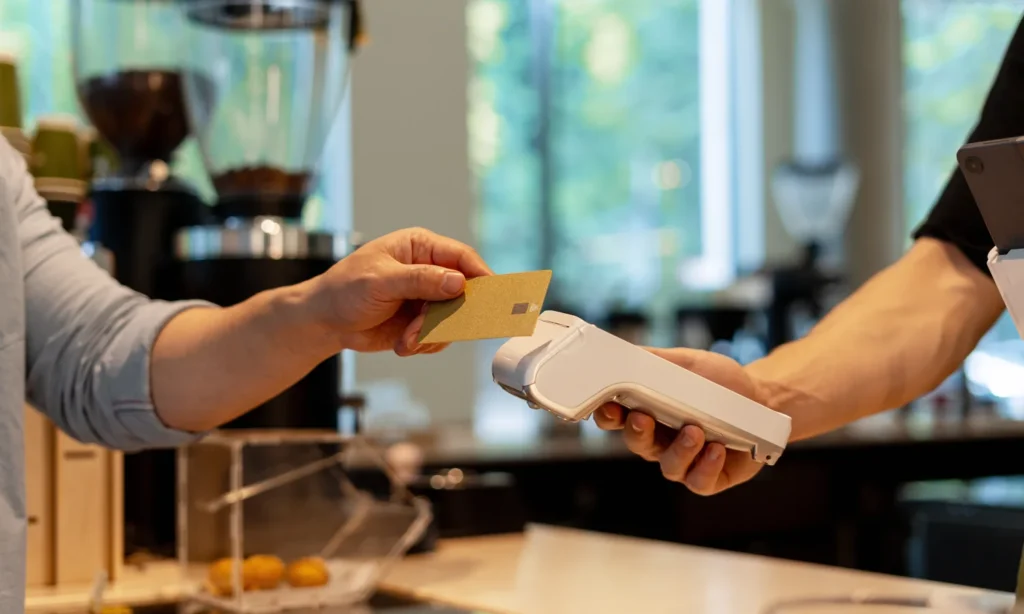
From 1 October, businesses can no longer add a surcharge to payments made with Visa, Mastercard, American Express or eftpos credit, debit or prepaid cards. The RBA has framed the change as a consumer win, saying it will save consumers $1.6 billion a year.
The fee itself hasn't gone anywhere. The ban does not stop banks, card networks or payment providers from charging businesses to process transactions. The cost has simply moved from the bottom of the bill to the price of every item on the menu.
What we're already seeing
The repricing is happening in real time. In Perth, The Oarhouse lifted the price of a 12-ounce coffee from $6 to $6.50, its first price increase in two years. Under the old model, a card customer paid about $6.11 including the surcharge, while a cash customer avoided the fee. That means a 6% increase for card users and more than 8% for anyone paying cash.
In Darlinghurst, media has reported that Peter Semaan of the Rusty Rabbit Cafe has raised food and cold drink prices by about $2 on average. The ABC has reported that restaurant owner Peter Papas has also lifted his prices and is worried some customers will walk away.
The RBA saw this coming. It anticipated that the 16% of merchants who surcharged would lift their advertised prices to cover the cost of accepting cards. It has also estimated the effect on headline inflation at about 0.1%, as a small, one-off impact.
That figure is small at the national level. In a restaurant, it is a very different story.
Why this hits hospitality harder than most
Hospitality runs on margins most industries would consider a rounding error. According to Restaurant & Catering Australia, the average restaurant made a net profit of just 2.6% last year.
Consider what that means for a venue that was surcharging 1.5% and takes almost all of its revenue on card. If that venue absorbs the fee, it gives up roughly half of its net profit. No operator can absorb that indefinitely, and very few will try.
That is why industry bodies have been blunt. ARCA CEO Wes Lambert has said that operators are left with two options, absorb merchant fees directly which they can’t, or increase menu prices across the board.
Our view: expect 3–5%, not 1.5%
The theoretical price rise is the surcharge itself, usually somewhere between 1% and 2%. We don't think that is what diners will see. Three things push the real number higher.
- The first is rounding. Nobody prices a flat white at $5.58. Operators move to the next clean price point, which turns a 1.5% cost into a 5–10% rise on low-ticket items like coffee, pastries and sides. The ABC has noted that venues are likely to raise prices by more than the old surcharge because of price rounding.
- The second is catch-up pricing. Many operators have held prices through two years of wage, rent and food inflation. The surcharge ban gives them a natural moment to reset the whole menu, and some will take it.
- The third is that the weekend surcharge survives. Hospitality businesses can still charge weekend and public holiday surcharges. For diners, the total weekend bill is unlikely to fall at all.
Putting this together, our estimate is a 3–5% effective menu increase across venues that previously surcharged, with coffee and small-ticket items closer to 7–10%. The industry knows the risk this carries. Restaurant & Catering Australia's John Hart has warned that operators fear resetting menu prices could push them to a point where demand falls.
The relief is real, but it's slow
There is some offsetting relief on the cost side. The RBA's reforms are expected to cut wholesale card payment costs for merchants by around $910 million a year through lower interchange caps. However, as the Retail Council has pointed out, how much this offsets the ban depends on how much payment providers actually pass through.
Operators should not wait for those savings to arrive on their own. From 30 October 2026, designated card networks and large payment acquirers must publish information about card-payment fees. When that data is published, use it to renegotiate your merchant agreement.
What this means for lenders and investors
This is a test of pricing power. Venues with loyal regulars and a clear point of difference will reprice and hold their trade. Venues competing on price in crowded strips will either lose covers or lose margin, and in our experience it is often both.
There are a few early warning signs worth watching over the next two quarters. Watch for venues that have not repriced at all, because they are absorbing a cost they likely cannot carry. Watch for venues that repriced aggressively and are now seeing covers fall. Combined with Payday Super already tightening cash flow, the surcharge ban is another pressure point that will bring underlying financial stress to the surface sooner.
What operators should do now
- Reprice deliberately. Rather than adding a flat percentage to everything, target the items where customers are least price-sensitive.
- Check your menu wording. The ACCC is clear that businesses must not give false or misleading information about prices or the reasons for a price increase.
- Renegotiate your merchant fees. Use the new fee transparency to push for lower rates, and don't assume interchange savings will be passed through automatically.
- Stress-test your cash flow. Model 5% fewer covers alongside your new pricing and see whether the venue still works.
The surcharge was never the problem. Thin margins were. The ban has simply made that fact visible on every menu in the country.
Olvera Advisors works with hospitality operators, lenders and investors on pricing, cash preservation and turnaround strategy, including our Rapid Cash Framework. If the new numbers aren't adding up, talk to us early.