Navigating Market Volatility in Health & Community 2026
- See where financial distress is concentrating - NDIS providers, aged care and allied health - and the funding mechanics driving it.
- Read the sector's hard numbers: a $44B NDIS market, 10.1% of GDP, 2.3M workers, and a 200%+ rise in disability-provider insolvencies since 2023.
- Use Olvera's strategic dashboards and restructuring frameworks to assess counter-party risk and find distressed-asset and consolidation opportunities.
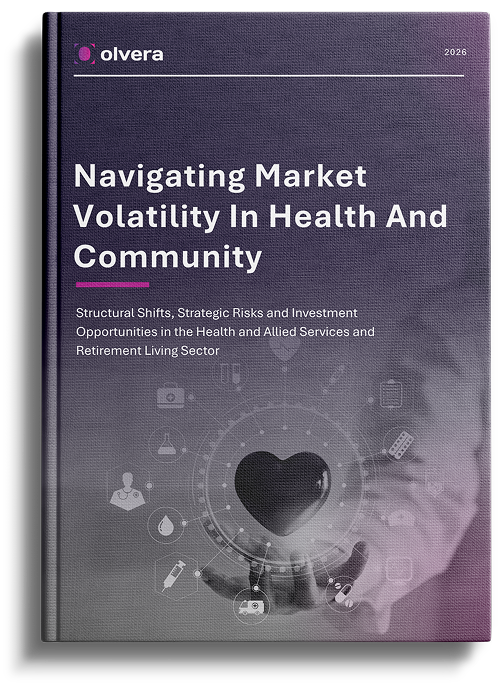
Send me the Report
Enter your details and we will send our report straight to your inbox.
Who's this report for
Written for the people exposed to Health & Community Risk.
Lenders & Workout Teams
Assessing credit risk in health and care portfolios, managing exposure to NDIS providers, aged care operators, and allied health groups under financial stress.
Investors, PE & Family Offices
Evaluating sector entry points, identifying distressed asset opportunities, and understanding the consolidation dynamics reshaping aged care, disability, and allied health.
Directors, Boards & Advisors
Navigating funding volatility, regulatory reform, and workforce pressures, or supporting providers through restructuring and turnaround.
NFP Executives & Care Providers
Understanding the structural forces driving financial distress across the sector and stress-testing your organisation's position against them.
$44B
Annual NDIS provider market (NDIA)
2.3M
Employed in health & social assistance - the nation's largest employer (ABS)
200%+
Rise in disability-provider insolvencies since 2023 (ASIC)
90,000
Aged-care beds short by 2040 (DoH)
WHAT’S INSIDE THE REPORT
Report insights & key takeaways
Understand the structural pressures
- Why capped NDIS pricing and Medicare rebate constraints collide with rising labour and compliance costs
- Where the federal/state funding split leaves hospitals and community care exposed
- How the shift to community-based care compresses margins through dispersed workforces and travel cost
- Why over half of disability providers reported no profit in 2024-25
Spot the capital opportunities
- Sector consolidation as smaller aged care, disability and allied-health operators exit
- Distressed-asset acquisition and recapitalisation across NFP and for-profit providers
- Retirement living and aged-care infrastructure — funding the 18,000-bed annual shortfall
- Integrated care precincts and digital-health plays with defensive demand
Apply the restructuring frameworks
- Counter-party risk assessment for health and NFP loan books and funder exposures
- Governance and Safe Harbour considerations specific to not-for-profit boards
- Turnaround levers for providers caught between fixed funding and rising costs
- Sector dashboards to benchmark a provider's distress against the market
About the Author
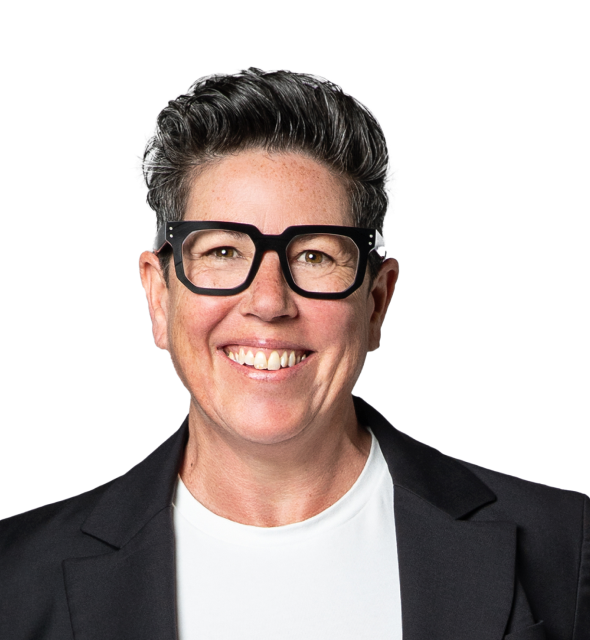
Kate Foy
Kate is a trusted strategic advisor and Principal at Olvera Advisors, drawing on an extensive career shaped within the NSW public sector.
With over 25 years across public service operations, her experience is inclusive of advising Boards and executives of industry peak bodies on engaging government, translating deep institutional insight into strategy that moves complex agendas forward.